How to Calculate Your Net Worth Step by Step
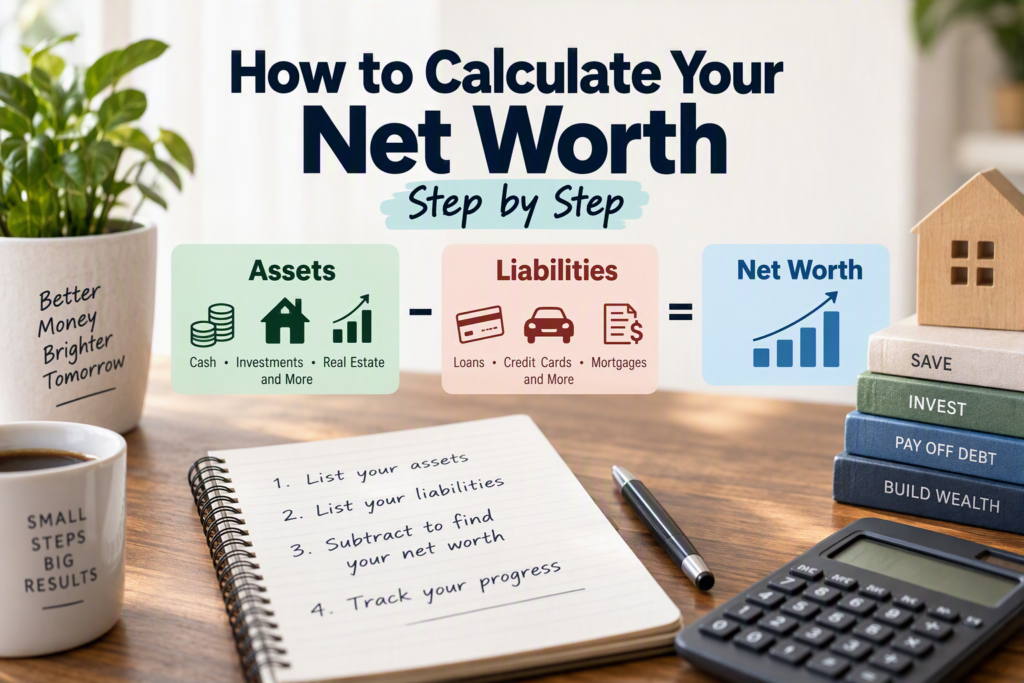
Knowing your net worth is one of the simplest ways to measure your financial health. Net worth is the value of everything you own minus everything you owe. If your assets are worth $100,000 and your debts total $40,000, your net worth is $60,000. Calculating it takes only a few steps, and regularly tracking it can help you make better decisions about saving, investing, spending, and paying off debt.
Whether you’re just starting your financial journey or already building wealth, understanding your net worth gives you a clear snapshot of where you stand today and where you may be headed in the future.
What Is Net Worth?
Net worth is the difference between your total assets and total liabilities.
Formula:
Net Worth = Assets − Liabilities
- Assets are things you own that have financial value.
- Liabilities are debts and financial obligations you owe to others.
Your net worth can be:
- Positive when assets exceed liabilities
- Negative when liabilities exceed assets
- Zero when assets and liabilities are equal
Many people assume income determines wealth, but net worth often provides a more accurate picture. Someone earning a high salary but carrying significant debt may have a lower net worth than someone with a modest income and substantial savings.
Why Calculating Your Net Worth Matters
Tracking net worth offers several benefits:
Measures Financial Progress
Income shows how much money you earn. Net worth shows how much wealth you have actually accumulated.
Helps Set Financial Goals
Knowing your starting point makes it easier to create realistic goals, such as:
- Saving for a home
- Building an emergency fund
- Paying off debt
- Planning for retirement
Identifies Problem Areas
A net worth calculation highlights debts that may be slowing your financial growth.
Encourages Better Financial Habits
People who track their finances regularly are often more aware of spending patterns and financial priorities.
Step 1: List All Your Assets
Start by creating a complete list of everything you own that has monetary value.
Cash and Cash Equivalents
Include:
- Checking accounts
- Savings accounts
- Money market accounts
- Cash on hand
Use current account balances.
Investment Accounts
Include:
- Stocks
- Bonds
- Mutual funds
- Exchange-traded funds (ETFs)
- Brokerage accounts
- Retirement accounts such as 401(k)s and IRAs
Use the current market value of each account.
Real Estate
Include:
- Primary residence
- Vacation homes
- Rental properties
- Land
Use a reasonable estimate of current market value. Online property valuation tools can provide a rough estimate, but professional appraisals offer greater accuracy.
Vehicles
Include:
- Cars
- Motorcycles
- Boats
- Recreational vehicles
Estimate present market value rather than the original purchase price.
Business Ownership
If you own a business, include your ownership stake’s estimated value.
Valuable Personal Property
Some people also include:
- Jewelry
- Collectibles
- Artwork
- Precious metals
- High-value electronics
For conservative estimates, use current resale value rather than replacement value.
Example Asset List
| Asset | Value |
|---|---|
| Checking Account | $5,000 |
| Savings Account | $15,000 |
| Retirement Account | $50,000 |
| Brokerage Account | $20,000 |
| Home | $250,000 |
| Car | $12,000 |
| Total Assets | $352,000 |
Step 2: List All Your Liabilities
Next, calculate everything you owe.
Mortgage Debt
Include the remaining balance on:
- Primary home mortgages
- Rental property mortgages
- Home equity loans
Auto Loans
Use the current loan balance rather than the original loan amount.
Student Loans
Include all federal and private student loans.
Credit Card Debt
Use your most recent statement balance or current balance.
Personal Loans
Include:
- Personal bank loans
- Family loans
- Peer-to-peer loans
Other Debts
Don’t forget:
- Medical debt
- Tax obligations
- Payday loans
- Business-related liabilities for which you’re personally responsible
Example Liability List
| Liability | Balance |
|---|---|
| Mortgage | $180,000 |
| Auto Loan | $8,000 |
| Student Loans | $15,000 |
| Credit Cards | $4,000 |
| Total Liabilities | $207,000 |
Step 3: Subtract Liabilities From Assets
Now apply the formula:
Net Worth = Assets − Liabilities
Using the examples above:
- Total Assets = $352,000
- Total Liabilities = $207,000
Net Worth = $352,000 − $207,000 = $145,000
In this example, the individual’s net worth is $145,000.
A Complete Worked Example
Let’s examine a more detailed example.
Assets
| Asset | Value |
|---|---|
| Checking Account | $3,500 |
| Savings Account | $12,000 |
| Investment Portfolio | $25,000 |
| Retirement Accounts | $60,000 |
| Home Value | $300,000 |
| Vehicle | $18,000 |
| Total Assets | $418,500 |
Liabilities
| Liability | Balance |
|---|---|
| Mortgage | $220,000 |
| Car Loan | $10,000 |
| Student Loans | $12,000 |
| Credit Cards | $2,500 |
| Total Liabilities | $244,500 |
Net Worth Calculation
$418,500 − $244,500 = $174,000
This person’s net worth is $174,000.
What If Your Net Worth Is Negative?
A negative net worth means your debts exceed your assets.
This situation is common among:
- Recent graduates with student loans
- Young professionals
- People recovering from financial hardship
- New homeowners with significant mortgage debt
A negative net worth is not necessarily a sign of financial failure. It simply reflects your current position.
How to Improve a Negative Net Worth
Focus on:
- Paying down high-interest debt.
- Increasing savings.
- Contributing to retirement accounts.
- Avoiding unnecessary borrowing.
- Growing income where possible.
Small improvements made consistently can gradually shift net worth into positive territory.
Which Assets Should You Include?
People often disagree about what belongs in a net worth calculation.
Commonly Included
- Cash
- Savings
- Investments
- Retirement accounts
- Real estate
- Vehicles
Sometimes Included
- Collectibles
- Jewelry
- Artwork
- Cryptocurrency holdings
Often Excluded
Some financial planners choose not to include household items such as:
- Furniture
- Clothing
- Everyday electronics
These assets can be difficult to value accurately and often have low resale value.
The most important factor is consistency. Use the same approach each time you calculate net worth so you can track progress accurately.
How Often Should You Calculate Your Net Worth?
Most people benefit from calculating net worth:
- Monthly
- Quarterly
- Semi-annually
- Annually
Monthly tracking provides the most detailed picture but may feel excessive for some people.
Quarterly reviews are often a practical balance between accuracy and convenience.
Avoid checking too frequently if short-term market fluctuations cause unnecessary stress.
Common Net Worth Mistakes
Using Purchase Price Instead of Current Value
A vehicle purchased for $30,000 may now be worth only $18,000.
Always use current market value.
Forgetting Debts
Leaving out credit cards, personal loans, or tax liabilities produces an inflated calculation.
Double Counting Assets
Do not count the same money twice.
For example, cash transferred from a savings account to an investment account should only be counted in its current location.
Ignoring Small Accounts
Old retirement accounts, forgotten savings accounts, or small investments can still contribute to your overall net worth.
Overvaluing Personal Property
Many personal possessions depreciate quickly.
Use realistic resale values rather than emotional estimates.
Net Worth vs. Income
These terms are often confused, but they measure different things.
| Factor | Net Worth | Income |
|---|---|---|
| Measures | Wealth accumulated | Money earned |
| Calculated From | Assets minus liabilities | Earnings over time |
| Changes Due To | Saving, investing, debt repayment | Salary, wages, business revenue |
| Time Frame | Snapshot of current position | Ongoing cash flow |
A high-income earner can have a low net worth if spending and debt are also high.
Similarly, someone with moderate income may build substantial wealth through disciplined saving and investing.
Net Worth vs. Liquid Net Worth
Some people track both traditional and liquid net worth.
Traditional Net Worth
Includes all assets and liabilities.
Liquid Net Worth
Only includes assets that can quickly be converted into cash, such as:
- Checking accounts
- Savings accounts
- Investments
It may exclude:
- Primary residence
- Vehicles
- Collectibles
Liquid net worth can provide a better picture of short-term financial flexibility.
Simple Net Worth Tracking Checklist
Use this checklist whenever you update your finances:
Assets
- Checking accounts
- Savings accounts
- Investments
- Retirement accounts
- Real estate
- Vehicles
- Other valuable property
Liabilities
- Mortgage balances
- Auto loans
- Student loans
- Credit cards
- Personal loans
- Tax obligations
- Other debts
Final Calculation
- Add total assets
- Add total liabilities
- Subtract liabilities from assets
- Record the result
- Compare with previous calculations
Tracking changes over time is often more valuable than focusing on a single number.
Ways to Increase Your Net Worth
Improving net worth generally comes down to increasing assets, reducing liabilities, or both.
Increase Assets
- Save a portion of every paycheck
- Invest regularly
- Contribute to retirement accounts
- Build emergency savings
- Develop additional income streams
Reduce Liabilities
- Pay extra toward high-interest debt
- Refinance expensive loans when appropriate
- Avoid unnecessary borrowing
- Pay credit card balances on time
Protect Your Wealth
- Maintain adequate insurance
- Build an emergency fund
- Diversify investments
- Monitor financial accounts regularly
Consistent habits usually have a greater impact than occasional large financial wins.
Frequently Asked Questions
What is a good net worth?
There is no universal number. A good net worth depends on factors such as age, income, location, and financial goals. A steadily growing net worth is generally a positive sign.
Should retirement accounts be included in net worth?
Yes. Retirement accounts are assets and are usually included when calculating net worth.
Does my home count as an asset?
Yes. Use the current estimated market value of the property and subtract any outstanding mortgage balance through the liability section.
Can my net worth change every day?
Yes. Investment values, property values, debt balances, and cash holdings can change frequently, causing net worth to fluctuate.
Is a negative net worth normal?
Yes. Many people experience negative net worth early in adulthood, especially if they have student loans or recently purchased a home.
Take the Next Step
Calculating your net worth is a straightforward process: add up everything you own, subtract everything you owe, and record the result. The real value comes from tracking that number over time. Regular updates can reveal trends, highlight progress, and help you make smarter financial decisions. Even if your current net worth is lower than you’d like, consistent saving, investing, and debt reduction can steadily improve your financial position year after year.