How to Calculate Your Monthly Savings Rate
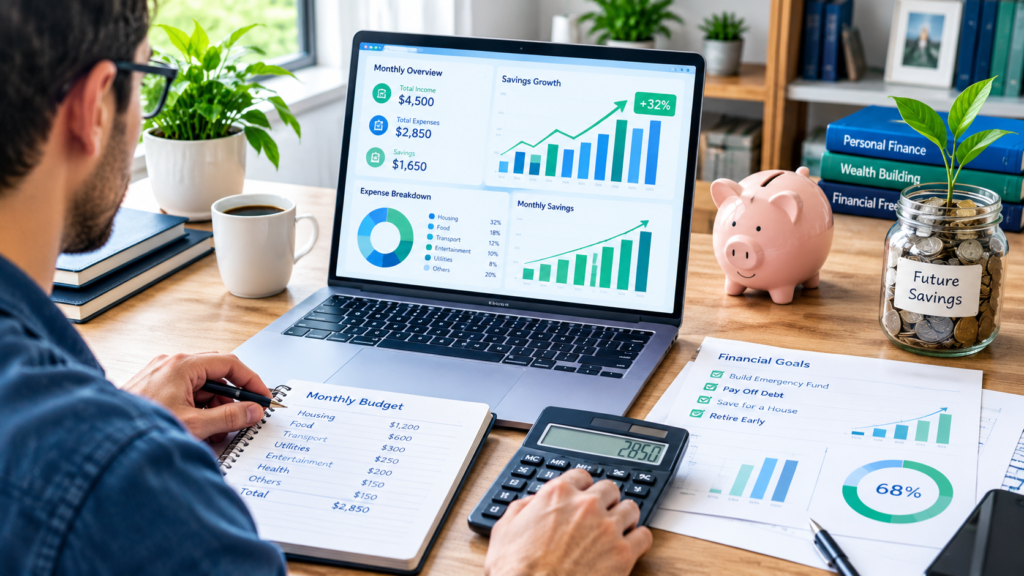
Your monthly savings rate is the percentage of your income that you save rather than spend. The basic formula is:
Monthly Savings Rate = (Monthly Savings ÷ Monthly Income) × 100
For example, if you earn $4,000 per month and save $800, your savings rate is 20%. Tracking this number helps you measure financial progress, set realistic goals, and understand whether your spending habits support your long-term plans.
What Is a Savings Rate?
A savings rate shows how much of your income is being set aside for future use. Instead of focusing only on the amount saved, it measures savings as a percentage of income.
This makes it easier to compare your progress over time, even if your income changes.
For example:
- Saving $500 per month may be excellent for someone earning $2,000.
- The same $500 may represent a much lower savings effort for someone earning $8,000.
By using a percentage rather than a dollar amount, you get a clearer picture of your financial health.
Why Your Monthly Savings Rate Matters
Your savings rate is one of the most useful personal finance metrics because it directly reflects the gap between what you earn and what you spend.
A healthy savings rate can help you:
- Build an emergency fund
- Reach financial goals faster
- Reduce dependence on debt
- Prepare for retirement
- Handle unexpected expenses
- Gain greater financial flexibility
Many people focus heavily on investment returns, but increasing your savings rate often has a greater impact in the early stages of building wealth.
The Basic Formula
The simplest calculation is:
Savings Rate = (Amount Saved ÷ Gross Income) × 100
Where:
- Amount Saved = Money added to savings, investments, retirement accounts, or other financial reserves during the month
- Gross Income = Total income before taxes and deductions
Example
Monthly income: $5,000
Monthly savings: $1,000
Calculation:
$1,000 ÷ $5,000 = 0.20
0.20 × 100 = 20%
Savings Rate = 20%
This means you save 20 cents for every dollar earned.
Gross Income vs. Net Income
One of the biggest sources of confusion is whether to use gross income or net income.
Using Gross Income
Gross income is your earnings before:
- Taxes
- Health insurance deductions
- Retirement contributions
- Other payroll deductions
Example:
- Salary: $6,000 per month
- Savings: $900
Savings rate:
$900 ÷ $6,000 × 100 = 15%
Many financial experts prefer gross income because it creates a consistent standard for comparison.
Using Net Income
Net income is what actually reaches your bank account after deductions.
Example:
- Gross income: $6,000
- Net income: $4,800
- Savings: $900
Savings rate:
$900 ÷ $4,800 × 100 = 18.75%
This method reflects how much of your take-home pay you save.
Which Method Is Better?
Neither approach is wrong.
Choose one method and use it consistently.
- Use gross income if you want easier benchmark.
- Use net income if you want a practical view of your available cash flow.
Step-by-Step Guide to Calculating Your Monthly Savings Rate
Step 1: Determine Your Monthly Income
Add all income sources received during the month, such as:
- Salary or wages
- Freelance income
- Side business income
- Rental income
- Bonuses
- Investment income
Example:
| Income Source | Amount |
|---|---|
| Salary | $4,500 |
| Freelance Work | $500 |
| Rental Income | $300 |
| Total Income | $5,300 |
Monthly income = $5,300
Step 2: Calculate Total Savings
Include money that increases your net worth, such as:
- Savings account contributions
- Retirement account contributions
- Investments
- Extra mortgage principal payments (optional depending on your method)
- Debt repayment above minimums (if considered wealth-building)
Example:
| Savings Type | Amount |
|---|---|
| Savings Account | $300 |
| Retirement Account | $250 |
| Investment Account | $200 |
| Total Savings | $750 |
Monthly savings = $750
Step 3: Apply the Formula
$750 ÷ $5,300 = 0.1415
0.1415 × 100 = 14.15%
Monthly savings rate = 14.15%
What Counts as Savings?
This question often creates confusion because not every transfer of money qualifies as true savings.
Usually Counts as Savings
- Contributions to savings accounts
- Retirement contributions
- Investment deposits
- Certificates of deposit (CDs)
- Money market accounts
- Emergency fund deposits
Usually Does Not Count
- Everyday checking balances
- Rent payments
- Utility bills
- Insurance premiums
- Credit card minimum payments
- Discretionary spending
The key principle is that savings should increase your future financial security or net worth.
Worked Example: A Full Monthly Budget
Consider this monthly financial situation:
| Category | Amount |
|---|---|
| Take-Home Income | $4,500 |
| Housing | $1,300 |
| Utilities | $250 |
| Food | $500 |
| Transportation | $350 |
| Entertainment | $250 |
| Savings Account | $500 |
| Retirement Contributions | $400 |
| Investments | $200 |
Total saved:
$500 + $400 + $200 = $1,100
Savings rate:
$1,100 ÷ $4,500 × 100 = 24.44%
In this example, the person saves approximately 24.4% of monthly income.
What Is a Good Savings Rate?
There is no single savings rate that works for everyone.
Your age, income, family situation, and financial goals all matter.
However, these general benchmarks can be useful.
| Savings Rate | General Interpretation |
|---|---|
| Under 5% | Low savings level |
| 5% to 10% | Building a savings habit |
| 10% to 20% | Strong progress |
| 20% to 30% | Excellent savings rate |
| Above 30% | Aggressive wealth-building |
These ranges are guidelines rather than strict rules.
Someone paying off high-interest debt may temporarily save less while still improving their financial situation.
How to Increase Your Savings Rate
If your savings rate is lower than you would like, focus on improving either side of the equation: earn more or spend less.
Automate Savings
Set automatic transfers immediately after payday.
Automation reduces the temptation to spend money that was intended for savings.
Track Spending
Review your bank and credit card statements.
Look for:
- Unused subscriptions
- Frequent takeout purchases
- Impulse shopping
- Recurring fees
Small expenses often add up more than expected.
Increase Income
Potential options include:
- Freelancing
- Overtime work
- Consulting
- Selling unused items
- Starting a side business
Additional income can significantly boost your savings rate when lifestyle inflation is controlled.
Reduce Major Expenses
Housing, transportation, and food typically make up the largest parts of a budget.
Even modest reductions in these categories can free up hundreds of dollars each month.
Direct Raises Into Savings
When income increases, send part or all of the raise directly into savings or investments before adjusting your lifestyle.
Common Savings Rate Mistakes
Counting the Same Money Twice
If money moves from checking into savings and then into an investment account, count it only once.
Double-counting can inflate your actual savings rate.
Ignoring Retirement Contributions
Employer-sponsored retirement accounts are often overlooked.
Including these contributions may provide a more accurate picture of your savings efforts.
Using Inconsistent Calculations
Switching between gross and net income can make long-term comparisons unreliable.
Use the same approach every month.
Forgetting Irregular Income
Freelancers, contractors, and business owners should include all income sources when calculating their savings rate.
Focusing on One Month
A single month may not represent your typical financial situation.
Track savings rates over several months to identify meaningful trends.
Savings Rate vs. Emergency Fund
These two concepts are related but different.
A savings rate measures how much you save each month.
An emergency fund measures how much savings you already have available.
For example:
- Person A saves 25% monthly but has only one month of emergency expenses saved.
- Person B saves 10% monthly but already has a fully funded emergency reserve.
Both metrics are valuable and should be tracked separately.
Savings Rate vs. Investment Return
A savings rate reflects behavior.
Investment returns reflect market performance.
Imagine two investors:
| Investor | Savings Rate | Annual Return |
|---|---|---|
| A | 25% | 6% |
| B | 5% | 10% |
Over time, Investor A may build more wealth simply because they contribute much more money consistently.
While investment returns matter, savings rate is often the factor you can control most directly.
Creating a Monthly Savings Rate Tracker
A simple spreadsheet can help you monitor progress.
Track:
| Month | Income | Savings | Savings Rate |
|---|---|---|---|
| January | $5,000 | $750 | 15% |
| February | $5,100 | $900 | 17.6% |
| March | $5,200 | $1,000 | 19.2% |
Reviewing several months of data can reveal:
- Spending trends
- Seasonal expenses
- Income fluctuations
- Progress toward financial goals
Even small improvements can have a meaningful impact over time.
Frequently Asked Questions
Should retirement contributions count as savings?
Yes. Retirement contributions generally count as savings because they increase your future financial assets and net worth.
Should debt payments count as savings?
Minimum debt payments usually do not count as savings because they are required obligations. Extra payments toward principal are sometimes included as wealth-building contributions, depending on the calculation method used.
How often should I calculate my savings rate?
Monthly tracking is ideal because it balances accuracy with simplicity and helps identify spending trends quickly.
Can my savings rate be negative?
Yes. If you spend more than you earn and withdraw money from savings, your savings rate can become negative.
Is a 20% savings rate good?
For many households, a 20% savings rate is considered strong and can support long-term goals such as retirement, investing, and major purchases.
Take the Next Step
Calculating your monthly savings rate requires only two numbers: how much you earn and how much you save. Once you know that percentage, you gain a clear measure of financial progress that is easy to track from month to month.
Start by calculating last month’s savings rate, then monitor it consistently. A modest improvement of just a few percentage points can add up to thousands of dollars in additional savings over time and bring your financial goals much closer to reality.